Smart tax and super planning before EOFY

Tax time is just around the corner, so now is the time to make sure you’re prepared for 30 June.

Each year, the ATO highlights its areas of focus. Taking a few minutes now to review these can help you avoid issues when lodging your return.

Work-related deductions under scrutiny

This year, the ATO is focusing on work-related deductions and income that’s not declared on tax returns.

If you are claiming work-related expenses, ensure they meet the ATO’s three golden rules:i

  1. The expense must be directly related to earning your income
  2. You must not have been reimbursed
  3. You must have records to support your claim, such as receipts or a logbook

For working from home expenses, you can use either the actual cost method or the fixed rate method.

Instant asset write-off

The instant asset write-off remains an important tax concession for Australian small businesses in the 2025–2026 financial year. Eligible businesses with an aggregated turnover of less than $10 million can immediately deduct the business portion of eligible assets costing less than $20,000, instead of depreciating them over several years. The asset must be first used or installed ready for use between 1 July 2025 and 30 June 2026.ii

Don’t overlook income

The ATO is also paying close attention to undeclared income. This includes:iii

  • Cash payments
  • Interest income
  • Rental income
  • Earnings from crypto assets

For those with a side hustle, check whether it may be considered a business. All business income, regardless of amount, is assessable and must be declared.iv

If you intend to claim deductions for business expenses related to your side hustle, ensure they are directly connected to earning that income and are supported by receipts.

Time for a portfolio review

Recent market volatility makes this a good time to review your investment strategy.

Checking your capital gains or losses before 30 June allows you to take action where appropriate.

For example, you may consider realising capital losses to offset gains from assets such as shares, property or crypto.

Tax timing strategies

If you have regular deductible expenses, such as investment loan interest or annual costs, it may be useful for some to prepaying them before 30 June to claim a deduction for this financial year.

You may also consider the timing of income expected before 30 June. Deferring income until after the end of the financial year may help reduce your tax liability.

Tax rates are also changing for lower income earners. From 1 July 2026, the rate for income between $18,201 and $45,000 will reduce from 16 per cent to 15 per cent, with a further reduction to 14 per cent the following year.

Super contribution strategies

The end of the financial year is an ideal time to review your super contributions.

If you plan to contribute before 30 June, check when your employer will make their contributions. The introduction of Payday Super means some employers are contributing earlier, which may affect your contribution caps.

For SMSF members, make sure that:

  • All contributions are received by the fund’s bank account by 30 June
  • Minimum pension payments are made
  • Asset valuations are up to date
  • Fund records are current

Be alert for tax time misinformation

The ATO is warning taxpayers to be cautious about the growing wave of tax “tips”, shortcuts and refund claims circulating online.

Content from social media, “finfluencers” and even artificial intelligence tools can sound convincing, but it is not always accurate or relevant to Australian tax law. Acting on this kind of advice can lead to incorrect claims, delays in processing returns and, in some cases, penalties.

Larger refunds, easy deductions or so-called “loopholes” should always be checked against trusted sources.

Ultimately, you are responsible for the accuracy of everything included in your tax return, regardless of where the advice came from.

Taking a few extra minutes to verify information before you lodge can help you avoid costly mistakes and keep your return on the right side of the rules.

Please get in touch if you need any help preparing for the end of the financial year.

Source: https://www.ato.gov.au

RBA Announcement – February 2026

At its latest meeting, the Reserve Bank Board announced it was increasing the cash rate to 3.85 per cent.

Please click here to view the Statement by the Monetary Policy Board: Monetary Policy Decision.

We’re watching closely what the banks do with their rates, as some of Australia’s biggest lenders may make changes to their rates.

Please get in touch if you would like to discuss recent rate movements or if you would like to review your finance options.

Your money, your priorities

Investing may be all about the numbers – growth, returns and risk – to build a secure future but increasingly investors are interested in an even more meaningful approach.

Four out of five respondents to a 2024 survey wanted their investments to have a positive impact in the world.i

The survey, by the Responsible Investment Association Australasia (RIAA), found 79 per cent of investors would be more likely to invest in funds or products that have been independently verified as responsible or ethical. Animal cruelty was a top concern for 66 per cent, followed by human rights abuses – 60 per cent, gambling – 56 per cent, companies that don’t paid their fair share of tax – 55 per cent, as well as tobacco, weapons and firearms all at 55 per cent.ii

This growing interest in responsible investment saw assets under management in Australian funds rise 24 per cent to more than $1.6 trillion in 2024.iii

Meanwhile, a 2025 survey of 3,500 high net worth Australian investors found that sustainable investing is gaining traction as long as appropriate returns, clear risk and return profiles, and transparent performance reporting are in place.iv

Adding value

Aligning your investments with your values isn’t about changing the way you invest, it’s about adding an extra layer of meaning to the process and shaping your portfolio to reflect what’s important to you.

For some, that might mean supporting companies that innovate responsibly or treat employees well. For others, it could mean avoiding industries that don’t align with their principles. There’s no single ‘right’ approach because your values are unique to you.

And here’s the reassuring part: investing with your values doesn’t mean sacrificing returns. Many businesses that operate with strong governance and long-term strategies have shown to perform competitively over time. So, you can pursue financial growth while feeling confident that your money is working in ways that matter to you.

In fact, the RIAA noted in 2024 a ten-year return on RIAA-certified products of 13.9 per cent, compared with 9.19 per cent for the rest of the market (Australian share funds).v

Of course, fundamental investment rules apply. Diversification is one of the keys to successful values-based investing. But it’s not about limiting your choices, it’s about finding the right mix of investments that meet both your financial and personal criteria.

A well-constructed portfolio can include companies across different sectors that align with your principles while still delivering strong performance. This approach ensures you’re not only investing with purpose but also managing risk effectively.

Taking the first step

Turning this idea into reality can be complex. Investor’s priorities are different and the investment universe is vast. That’s where a financial adviser adds value.

A good adviser doesn’t just manage numbers. They listen and take the time to understand what matters most to you, whether that’s supporting certain industries, avoiding others or balancing ethical considerations with performance goals.

From there, they help design a strategy that reflects your values without losing sight of your financial objectives.

Advisers also provide clarity. With so many investment options available, it’s easy to feel overwhelmed. We can help you navigate choices, evaluate trade-offs, and ensure your portfolio remains diversified and resilient. We can also monitor your investments regularly, making adjustments as markets change and your priorities evolve.

So, if you’ve ever wondered whether your investments reflect your values, you can begin exploring the possibilities.

Start by asking yourself about the principles that are most important to you; the industry sectors you would like to support or steer clear of and how you would define success.

Then, give us a call. We can help you to align your portfolio with your values while keeping your long-term goals on track.

i, ii From Values to Riches 2024: Charting consumer demand for responsible investing in Australia – Consumer Research

iii, v Record $1.6 trillion committed to responsible investing, but greenwashing remains a major concern – Media Release

iv New EY survey: Australian investors more likely to stick with their adviser, though shifting expectations are reshaping the wealth management landscape | EY – Australia

Market movements and review video – November 2025

Stay up to date with what’s happened in the Australian economy and markets over the past month.

Australia’s economy remained under pressure in October. Investors sharply pared back future rate-cut bets after inflation data came in higher than expected.

News of the higher-than-expected inflation numbers was followed by the biggest daily fall in the Australian share market in two months.

Wall Street ended the month subdued over suggestions of no further rate cuts expected this year but there was some optimism about US-China relations.

Click the video below to view our update.

Please get in touch if you’d like assistance with your personal financial situation.


Market movements and review video – August 2025

Stay up to date with what’s happened in the Australian economy and markets over the past month.

Interest rates and tariffs continue to influence markets globally.

After the RBA’s surprise move to leave rates on hold at its July meeting, soft inflation data has paved the way for a future rate cut.

The ASX 200 climbed to a fresh record high during the month of July. Wall Street also recorded all-time highs as tariffs begin to be locked in and AI investment takes off.

Click the video below to view our update.

Please get in touch if you’d like assistance with your personal financial situation.

MONEY TALK PLANNERS TO JOIN RGM

RGM are proud to announce that financial advisory firm Money Talk Planners will be joining forces with RGM come the 1st of July 2025.

Money Talk Planners is a locally, family-owned financial planning business based out of Morwell that has been in operation for over 30 years. It has a reputation of providing high quality advice to its clients in a professional manner; values that underpin the services we provide at RGM. With the move, the entire Money Talk Planners team will reside in our Traralgon office.

There will be no change to the existing service provided to all our financial planning and accounting clients. Joe Auciello, Partner of over ten years in both our accounting and financial planning divisions, explains why RGM sought out this alliance. “In the ever-growing financial advisory sector, it is imperative that as a business, we look at strategic moves to ensure we can bolster our service offering to existing and new clientele. The Money Talk Planners team will bring their own ideas across to RGM that we look forward to incorporating into our business. Over the past two years we have been diligently working in the background to ensure that this move puts RGM at the forefront of financial planning in Gippsland both now and into the future”.

As part of the move, MTP practice principal Tony Salvatore and financial advisor Adrian Salvatore will join the ownership group of RGM. With over 30 years of financial of financial planning experience, Tony is excited about the move. “Both businesses have shared values, and we will be able to offer enhanced resources, greater financial guidance and invest quality time with our clients. It will be business as usual.”

We formally welcome the Money Talk Planning team across to RGM and we’re all excited in what the future holds!

Big changes ahead for Aged Care

The number of Australians aged over 65 is expected to more than double in the next 40 years while the number of people aged over 85 is predicted to triple in that time.i

Aged care funding and services have seen major changes in the years since the 2021 report of the Royal Commission into Aged Care Quality and Safety, and this year is no exception.

1 July 2025 marks the start of a host of new programs and improvements for the aged care sector. Several announcements have already been made this year, covering wage rises for aged care workers and nurses, and an increase in government funding for residential aged care accommodation.

In one of the most significant changes, the new Aged Care Act begins on 1 July. The Act aims to ensure the viability and quality of aged care.

A report by the Aged Care Taskforce last year calculated the residential aged care sector will need $56 billion by 2050 to upgrade facilities and build more rooms.

Current funding arrangements aren’t working. In the 2022-2023 financial year, almost half of all accommodation providers made a loss.

Some $300 million in federal grants will be delivered to accommodation providers this year to help with capital works upgrades.

And to improve the viability of the facilities the government is introducing other measures including larger means-tested contributions from new entrants and a higher maximum room price that is indexed over time.

Aged Care Minister Anika Wells says half of new residents will not contribute more under the new consumer contributions.

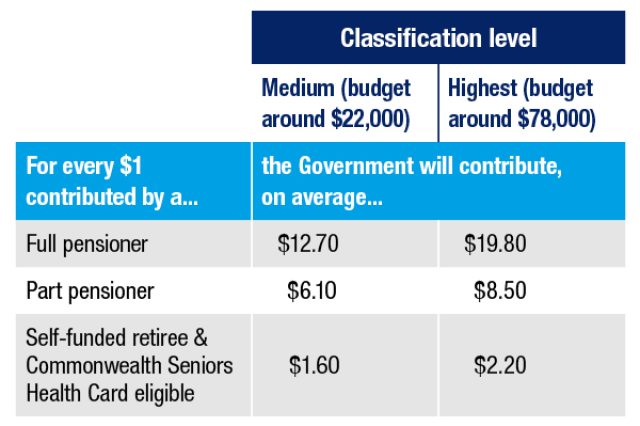
“For every $1 an older Australian contributes to their residential aged care, the government will contribute an average of $3.30,” says Wells.

Support at Home

The Aged Care Act also aims to support more people who want to stay in their own homes as they age. The federal government is investing $4.3 billion in a new Support at Home program, which replaces the Home Care Packages and the Short-Term Restorative Care programs.ii

There’ll be more than 300,000 places available over the next 10 years and a shorter waiting period for Support at Home, and there’s a goal to simplify and improve the assessment process, making it easier to access different services as needs change.iii

Similar to the Home Care Package, Support at Home will provide:

  • clinical care, such as nursing and occupational therapy,
  • help with maintaining independence including showering, dressing and taking medications, and
  • support for everyday living tasks such as cleaning, gardening, shopping and meal preparation.

The government will pay 100 per cent of clinical care costs while Support at Home recipients will make a contribution towards independence and everyday living costs. The contribution amount will be calculated using the Age Pension means test and it depends on the level of support needed and the combination of income and assets. The highest classification with the most funding will receive a package of services worth $78,000 per year. There’ll also be funding for assistive technology and home modifications and end of life care.

A new cap on contributions will also apply. No one will pay more than $130,000 in their lifetime – whatever their means or length of care at home or in residential accommodation.

Refunding deposits

The new Aged Care Act also requires aged care accommodation providers to refund residents’ lump sum deposits within 14 days if they move to another facility or pass away. Interest must be paid on the lump sum until the amount is repaid. As before, some deductions are permitted provided they were included in the original agreement.

No disadvantage

For those already receiving home care packages or in aged care accommodation, the government says a ‘no-worse-off’ principle will provide certainty that they won’t have to pay more under the new laws.

Whether it is you or a loved one who is considering moving into aged care, it can be an emotional time. With these new changes being implemented, you may have a few questions. Please give us a call if you’d like to hear more about the changes or if we can help to assess your next step or plan ahead.

Once in a generation aged care reforms | Health Portfolio Ministers | Australian Government Department of Health and Aged Care

ii Support at Home program | Australian Government Department of Health and Aged Care

iii About the Single Assessment System for aged care | Australian Government Department of Health and Aged Care

Federal Budget 2025-26: Spotlight on tax

In the shadow of an upcoming election, Jim Chalmers’ fourth Budget delivered small but unexpected tax cuts for all Australian taxpayers.

The modest cuts were delivered against a backdrop of growing economic uncertainty, with the treasurer emphasising the need for national resilience in the face of rapid global change.

Tax cuts for everyone

In a surprise revelation, the treasurer announced two new tax cuts in the 2025 Budget.

The first is a cut in the lowest personal income tax rate, which covers every dollar of a taxpayer’s income between $18,201 and $45,000. The current 16 per cent rate will reduce to 15 per cent in 2026-27 and be lowered again to 14 per cent from 1 July 2027.

According to the government, the reduction will take the first tax rate down to its lowest level in more than half a century. Combined with the 2024 tax cuts, an average earner will be paying $2,190 less in 2027-28 compared with 2023-24.

The second tax cut is an increase of 4.7 per cent to the Medicare low-income threshold for singles and families. This means the Medicare Levy will not kick in until singles earn $27,222, rather than the current $26,000 level. The threshold for families will rise from $43,846 to $45,907, while single seniors and pensioners will have their threshold increase from $41,089 to $43,020.

Energy relief for small business and households

The Budget also provided small businesses and households with a welcome additional energy bill rebate to cope with the burden of high energy costs.

Around one million eligible small businesses will receive an additional $150 directly off their energy bills from 1 July 2025. This will extend the government’s energy bill relief until the end of 2025, as the previous rebate scheme was due to end on 30 June.

Abolition of non-compete clauses and licensing reform

Some businesses may be less pleased with the Budget announcement of a planned ban on non-compete clauses covering low- and middle-income employees leaving for another business or to start their own.

Competition law will be tightened to prevent businesses making arrangements that cap workers’ pay and conditions without their knowledge or agreement, or that block them from being hired by competitors. The government claims this will increase affected employees’ wages by up to 4 per cent as they will be able to move to more productive, higher-paying jobs.

Work will also begin on a national occupational licence for electrical trades, which is intended to provide a template for other industries where employees are currently restricted from working across state and territory borders.

Beer excise freeze

Government support for the hospitality sector and alcohol producers was also announced in the Budget.

Indexation of the draught beer excise and excise equivalent customs duty rates will be paused in a measure costing about $165 million over five years.

Strengthening competition law

Small business will benefit from the government’s decision to work with the states and territories to extending unfair trading practices protections to small businesses.

Over $7 million will be provided over two years to strengthen the Australian Competition and Consumer Commission’s enforcement of the Franchising Code.

Subject to consultation, protections from unfair contract terms and unfair trading practices will be extended to all businesses regulated by the Franchising Code.

Supporting Australian businesses

Local companies will also benefit from $20 million in additional support for the Buy Australian Campaign, which encourages consumers to buy Australian-made products.

The Budget further supported local businesses with $16 million in funding for a new Australia-India Trade and Investment Accelerator Fund.

Additional ATO tax compliance funding

The ATO will be happy, with the 2025 Budget providing $999 million over the next four years to extend and expand its tax compliance activities.

This includes additional funding for the shadow economy and personal income tax compliance programs, together with $50 million from 1 July 2026 to ensure the timely payment of tax and unpaid super liabilities by businesses and wealthy groups.

Information in this article has been sourced from the Budget Speech 2025-26 and Federal Budget Support documents.  


It is important to note that the policies outlined in this article are yet to be passed as legislation and therefore may be subject to change. 

How to master FBT compliance

Preparing for the Fringe Benefits Tax (FBT) year-end is never a walk in the park and, with the ATO now using increasingly sophisticated data matching programs, it is more important than ever to get your return right.

As part of the ATO’s post-pandemic campaign to improve taxpayer compliance and payment of tax debts, the ATO is using data matching tools to check whether businesses should be reporting employee fringe benefits and paying tax on them.i

As a small business owner, you shoulder full responsibility for accurately calculating the taxable value of all fringe benefits, lodging the FBT return, paying any required tax, and reporting fringe benefits on an employee’s payment summary if the individual benefits exceed $2,000.ii

Areas to check in your FBT return

Vehicle benefits are a continuing source of mistakes when it comes to FBT returns. The ATO is particularly interested in commercial vehicles (mainly dual cab utes) provided to employees. Many employers wrongly believe these vehicles are fully FBT-exempt. But an exemption only applies where private use of the vehicle is minor and infrequent.

FBT rules about the use of employee car parking have also been tightened. FBT usually applies if you provide your employees with parking in a commercial car park, although many small businesses are eligible for an FBT exemption under specific conditions.iii

Dining and EV benefit rules

Entertainment and in-house dining fringe benefits are another area where it’s easy to be caught out.

Ensure you have detailed records related to these types of benefits (including any contributions made by employees) and check the benefits provided have met the ‘minor and infrequent‘ rule.

Also keep an eye on the implications of new rules covering electric vehicle (EV) benefits.

Getting employees to play their part

To simplify the process of putting your FBT return together, it helps if your employees play their part.

For example, encourage employees who use salary packaging to spend all of their available annual balance before 31 March to avoid the headache of unspent or claimed benefits rolling over into the next FBT year.

If employees do not use their unspent balance, it still needs to be reported and deducted from their cap limit in the new FBT year, which can create additional paperwork.

Employee declarations

If you plan to use the FBT exemptions and concessions on offer, you may also need to obtain detailed records from your employees (such as travel diaries, logbooks, declarations and odometer records).iv

Any change in car usage due to a new work role needs to be noted and the business use percentage adjusted, or a new logbook started.

Start collating this information as early as possible to simplify the calculation and lodgement process.

Meeting the lodgement deadline

Unlike the normal tax year, the FBT year ends on 31 March, with the 21 May lodgement and payment deadline giving you only a short window to get your paperwork in order. If you lodge with an accountant the deadline is 25 June.

You need to determine the taxable value of the different fringe benefits your employees have received during the year, calculate the tax you need to pay and collect any required employee declarations.

All employee declarations must be obtained by the time your FBT return is due to be lodged. Even if you do not have to lodge a return, you must have the declarations by 21 May.

We can help with any questions you may have and assist you with preparing your FBT return.

 i Addressing collectable tax debt – Tax Institute’s Tax Summit 2023 | Australian Taxation Office

ii Reportable fringe benefits | Australian Taxation Office

iii Fringe benefits tax – a guide for employers | Legal database

iv Employee declarations | Australian Taxation Office